QUICK ANSWER
Work through it in this order. First, check whether storm damage makes it an insurance claim. Second, stabilize the roof temporarily so water damage stops compounding while you sort out money. Third, confirm whether you actually need a full replacement or whether a repair buys you a season or two. Only then look at how to pay. Rural Pennsylvania homeowners may qualify for USDA Section 504 loans at a fixed 1% rate, or grants if they’re 62 or older. PHFA’s HEELP loan covers roof replacement at a fixed 1% APR, but only through a PHFA-approved contractor. County programs, Area Agencies on Aging, and PA 211 are worth calling. Financing – contractor, home equity, or personal loan – comes after you’ve checked what assistance exists. One thing not to do: nothing. Water damage compounds fast, and a deferred roof becomes a roof plus decking plus drywall plus insulation.
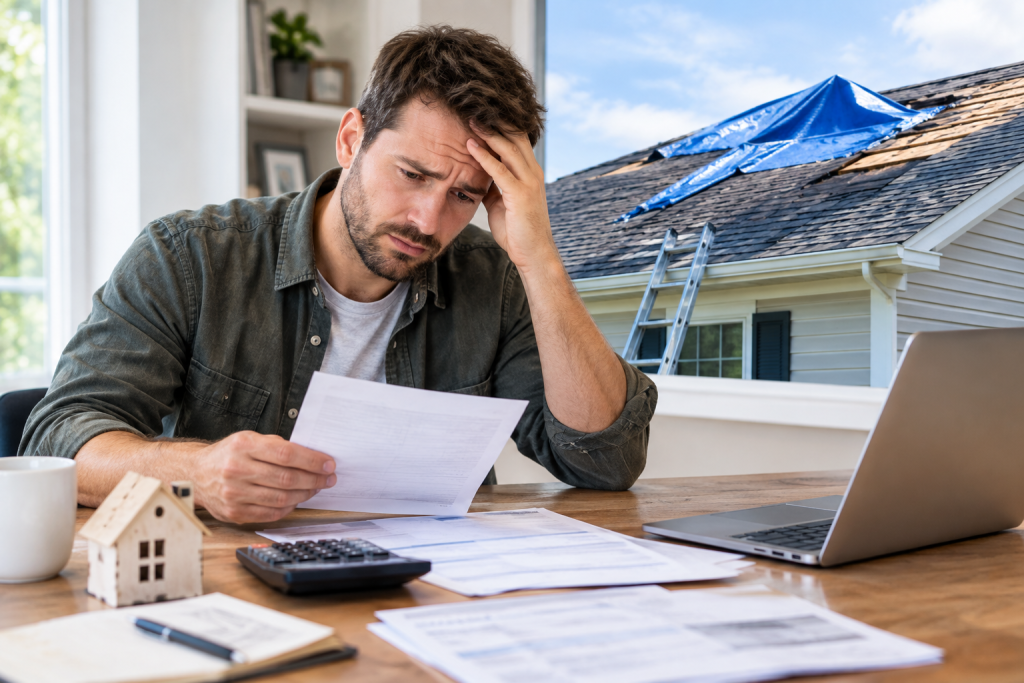
A roof rarely fails on a convenient schedule. It fails in February, or the week the car needed work, or right after you’d spent the savings on something else.
If you’re reading this with a bucket in the hallway, here’s the practical order of operations – including several Pennsylvania programs most homeowners have never heard of.
First: Is This an Insurance Claim?
Before anything else, establish whether the damage is storm-related.
Wind, hail, and fallen limbs are typically covered perils. Gradual wear and age are not. The distinction matters enormously, and it isn’t always obvious from the ground – a roof that seems simply old may have storm damage on it that an experienced eye can identify and document.
Photograph everything, note the date of any storm you can connect it to, and get an inspection before you call your insurer. Our guide to how the insurance claim process works for PA roof damage walks through what to expect.
One firm warning. If any contractor offers to waive, absorb, or “eat” your deductible, walk away. That can constitute insurance fraud, and you’re exposed alongside them.
Second: Stop the Damage While You Decide
This is the step people skip, and it’s the expensive one to skip.
An active leak doesn’t pause while you arrange financing. Water moves into decking, insulation, drywall, and framing, and every week of delay adds to the eventual scope. Emergency tarping or a temporary patch is comparatively minor work, and it buys you the time to make a good decision instead of a panicked one.
Ask any contractor whether they’ll stabilize the roof now and schedule the full work later. Most reputable ones will.
Third: Do You Actually Need a Full Replacement?
Sometimes yes. Often not yet.
A localized failure on an otherwise sound roof can frequently be repaired, giving you a season or several to plan properly. A contractor who inspects a fifteen-year-old roof with one bad section and immediately quotes a full tear-off is not necessarily wrong – but you’re entitled to hear the reasoning and the alternative.
Our guide to telling repair from replacement covers how that call gets made. Get a second opinion if the first one feels rushed.
Assistance Programs Worth Checking
Most homeowners never look here, and in rural Western Pennsylvania some of these are genuinely accessible. Program rules and funding change, so confirm current status directly with each one.
USDA Section 504 Home Repair
The most reliable option for rural homeowners, and much of our service area qualifies as rural under USDA’s definition.
It offers loans to low and very-low-income homeowners for repairs, and grants to homeowners aged 62 and older to remove health and safety hazards. A failing roof generally qualifies as a health and safety issue rather than a cosmetic upgrade.
To be eligible you must own and occupy the home, be unable to obtain affordable credit elsewhere, and have household income below the limit for your county.
The current terms, straight from USDA:
- Maximum loan: $40,000, termed for 20 years at a fixed 1% interest rate
- Maximum grant: $10,000, with a lifetime limit at that figure
- Loans and grants can be combined for up to $50,000 in total assistance
- Full title service is required if your total outstanding 504 balance exceeds $25,000
- Applications are accepted year-round through your local Rural Development office
One condition people miss: grants must be repaid if you sell the property within three years. Worth knowing before you apply if a move is on the horizon.
Check your address on the USDA eligibility site first, then contact your local Rural Development office to start an informal prequalification.
PHFA HEELP
The Pennsylvania Housing Finance Agency’s Homeowners Energy Efficiency Loan Program lends from $1,000 to $10,000 at a fixed 1% APR over ten years, with no prepayment penalty – and roof replacement is explicitly listed as eligible work, alongside insulation, air sealing, windows, doors, and heating or cooling systems.
Income limits apply, though PHFA can make exceptions up to 150% of area median income depending on circumstances. There’s a self pre-screening form on their site if you want to test eligibility before committing to an application.
Two things that matter practically:
- Do not let work begin before the loan closes. PHFA states this plainly, and starting early can disqualify you.
- Your contractor has to be PHFA-approved. All contractors working with HEELP borrowers must be on their approved list, which is searchable by county. Check before you choose a roofer, not after.
PHFA’s Solution Center is 855-827-3466.
PHFA also runs broader Renovate & Repair loans with higher limits and longer terms.
County and local programs
Allegheny County homeowners should look at AHILP. Other counties run their own rehabilitation programs through community action agencies, with rules and funding that vary considerably by location.
PA 211 and your Area Agency on Aging
Dial 211 or visit pa211.org to be routed to whatever exists in your county. If you’re a senior, your county Area Agency on Aging often knows about programs that never appear in a web search. Habitat for Humanity affiliates in some counties also run home repair programs.
One program to skip
You’ll find a lot of articles pointing to Pennsylvania’s Whole-Home Repairs Program. As of 2026 it’s largely closed – it was a one-time, federally funded program, the money is nearly exhausted, a state-funded successor has been left out of the budget repeatedly, and many county waitlists are shut.
It’s still worth one phone call to your county agency, because a few local pockets of funding remain. Just don’t build your plan around it.
Financing Routes
If assistance doesn’t fit, these are the common paths. None is universally right – it depends on your equity, your credit, and your timeline.
Contractor financing. Convenient and fast, arranged through the roofer’s lending partner. Ask three questions: what’s the actual APR after any promotional period, is there a prepayment penalty, and is this deferred interest? Deferred-interest offers can retroactively charge all accrued interest if the balance isn’t cleared in time, which is the trap in these products.
Home equity loan or HELOC. Typically the lowest rates available because the loan is secured – which is also the risk, since your home is the collateral. Slower to close.
Personal loan. Unsecured, so your house isn’t at stake, generally at higher rates. Faster than home equity.
Credit card. Fastest, most expensive, and worth using only as a bridge you have a concrete plan to clear.
Phasing the work. Underused. Stabilize now, replace the worst elevation, complete the rest next season. Not ideal, but far better than a leak running for a year.
We’re not financial advisors, and none of this is a recommendation – talk to your bank or credit union about your own situation. They’ll often beat contractor financing.
Red Flags When You’re Under Pressure
Financial stress is what predatory contractors look for. Watch for:
- Door-knockers after a storm offering immediate free inspections
- Pressure to sign today for a price that expires
- Large deposits demanded up front before materials are ordered
- Deductible waiving offers
- No written scope – just a number
- No Pennsylvania HIC registration – every legitimate contractor has one, verifiable in seconds, and we explain why the HIC number matters
A contractor who won’t wait a week for you to arrange financing properly is telling you something about how they operate.
Frequently Asked Questions
Can I get a grant to replace my roof in Pennsylvania?
Possibly. USDA Section 504 offers grants to rural homeowners aged 62 and older for health and safety hazards. Most other programs are loans rather than grants.
Does homeowners insurance cover a worn-out roof?
Generally no. Insurance covers sudden damage from storms, hail, or falling objects – not gradual wear or age. Get an inspection to determine which you’re dealing with.
What is PHFA HEELP?
A Pennsylvania Housing Finance Agency loan from $1,000 to $10,000 at a fixed 1% APR over ten years. Roof replacement qualifies, but your contractor must be PHFA-approved.
Is the Whole-Home Repairs Program still available?
Largely no. Its one-time federal funding is nearly exhausted and many county waitlists have closed. Still worth one call locally, but don’t rely on it.
Can I replace part of my roof now and the rest later?
Often yes. Phasing isn’t ideal, but stabilizing the roof and replacing the worst section beats letting a leak run while you save.
Talk to Us Before You Panic
We’d rather walk your roof and tell you it has two more seasons in it than sell you something you can’t afford. If it genuinely needs replacing, we’ll help you understand what’s urgent and what can wait.
Cambria Exteriors provides roof replacement and roof repair across Cambria, Somerset, Blair, Indiana, Westmoreland, and Clearfield counties. We offer financing options, discounts for seniors, teachers, and first responders, and free inspections – and every project contributes to our Roofing for a Reason™ program supporting local families.
Get a free quote or call 814-517-8281.